
In today’s fast-paced world, financial management can often become overwhelming. Many individuals find themselves juggling multiple debts, each with varying interest rates and monthly payments. This is where personal loans for debt consolidation come into play, offering a lifeline to those struggling to manage their finances. In this article, we’ll explore how personal loans can simplify your financial obligations, help you save money, and provide a clear path towards financial freedom.
Understanding Debt Consolidation
Table of Contents
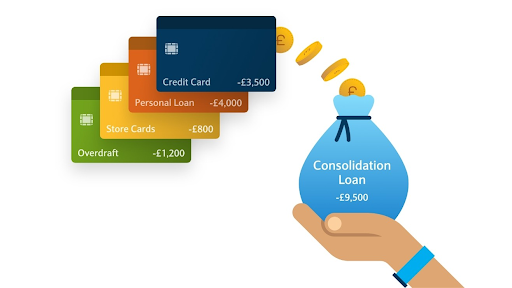
Debt consolidation involves combining multiple debts into a single loan, ideally with a lower interest rate. This is particularly beneficial for individuals who have numerous EMIs (Equated Monthly Installments) due to various loans, credit cards, or other financial commitments. By consolidating these debts into one personal loan, you can streamline your finances and focus on a single payment, allowing for easier budgeting and management of your debts.
The Role of Personal Loans in Debt Consolidation
1. Simplifying Payments
One of the most significant advantages of using personal loans for debt consolidation is simplification. With a personal loan, you only have to make one payment each month rather than multiple payments to various creditors. This helps to reduce the stress of managing various due dates and minimizes the chances of missed payments, which can harm your credit score.
2. Lowering Interest Rates
Personal loans often come with lower interest rates compared to credit cards and other forms of debt. By consolidating your debts into a personal loan, you may be able to reduce your overall interest expenses, leading to savings over time. For example, if you have credit card debts with interest rates as high as 20% or more, consolidating them into a personal loan with an interest rate of 10% can result in significant interest savings.
3. Fixed Monthly Payments
Most personal loans come with fixed interest rates, which means your monthly payments will remain constant for the loan’s duration. This predictability in payments can help you budget better and plan your financial future confidently. Fixed payments make it easier to manage your finance compared to variable-rate loans, whose payments can fluctuate based on market conditions.
4. Improving Credit Scores
Managing multiple debts can adversely affect your credit score due to high credit utilization and the potential for missed payments. By consolidating your debts and paying them off with a personal loan, you can lower your credit utilization ratio and improve your payment history. Over time, this can lead to a healthier credit score, enabling you to secure better loan terms for future financial needs.
Steps to Obtain a Personal Loan for Debt Consolidation
1. Assess Your Current Financial Situation
Before applying for a personal loan, take stock of your current debts, including outstanding balances, interest rates, and monthly payments. Understanding your total debt burden will help you determine the amount you need to borrow for consolidation.
2. Research Lenders
Loan terms, interest rates, and eligibility requirements can vary significantly among lenders. Research multiple options, including banks, credit unions, and online lenders, to identify the best fit for your needs. Consider factors such as interest rates, processing fees, and repayment terms.
3. Check Your Credit Score
Your credit score plays a crucial role in determining your eligibility for a personal loan 10000 and the interest rates you may qualify for. Obtain a copy of your credit report and check your score. If your score is not up to par, consider taking steps to improve it before applying for a loan to secure a more favorable rate.
4. Gather Necessary Documentation
Lenders typically require documentation to assess your income, employment status, and creditworthiness. Collect documents such as pay stubs, tax returns, and bank statements to streamline the application process.
5. Apply for the Loan
Once you’ve found a suitable lender and prepared your documentation, you can proceed with submitting your application. Ensure that you provide accurate information to avoid delays in processing.
6. Use the Funds Wisely
If approved, promptly use the funds from your personal loan to pay off existing debts. This step is crucial to ensure you capitalize on the benefits of consolidation. Avoid accumulating new debt during this time to maintain your financial health.
The Impact of Personal Loans on Financial Management
Utilizing personal loans for debt consolidation can significantly impact your overall financial management. By simplifying your payment structure, lowering your interest rates, and improving your credit score, you take control of your financial future.
Financial discipline is essential once you’ve consolidated your debts. Create a budget that accommodates your new fixed monthly payment while ensuring you don’t revert to your old spending habits. Building an emergency fund can also offer a safety net for unforeseen expenses, reducing the reliance on credit.
Conclusion
In summary, personal loans for debt consolidation can offer significant relief to those struggling with multiple EMIs, high-interest debts, and complicated payment structures. They streamline financial obligations, lower monthly payments, and provide a clearer path towards financial stability. However, it’s essential to approach debt consolidation with careful planning and diligence to maximize the benefits. With proper research, budgeting, and financial discipline, personal loans can be an effective tool for reclaiming control of your finances and working towards a debt-free future.

